Behind on your mortgage, or owe more than your home is worth?

I’m Jake Gregory. Let’s look at the options — including short-sale negotiation with your lender, and free help if keeping the home may still be possible.

Run by Jake Gregory personally, not a company.

If you want free, independent counseling first, contact a HUD-approved housing counselor at hud.gov/housingcounseling or 800-569-4287. That is a separate service. I am not a HUD-approved counselor and I am not affiliated with HUD or any other government agency.

Who this is for

Behind on payments, or would a sale not cover what you owe?

You don’t have to have everything figured out to start a conversation. These are the situations I hear most often.

Homeowners

You are behind on payments. You have a notice of default or a sale date. You inherited a house with a mortgage. You are separating or divorcing and the house will not sell for what is owed. A HELOC, HOA bill, or other lien is in trouble even if the first mortgage still looks current. Or you simply cannot tell whether any equity is left. Start with the form. Bring the latest mortgage statement and any letters you have. We will sort the dates and the options first. This is not a pitch to buy your house.

Family or friends

You are helping someone in one of those situations. You can start the form on their behalf. I will still need to hear from the people on the loan and the title before anything is signed.

Professionals

If you are a foreclosure, bankruptcy, divorce, or probate attorney, a real estate agent, or an investor with a homeowner who needs the lender side handled, jump to how I work with you. I do not pay referral fees.

The options, in plain words

Told there’s only one door? There are usually several.

The right one depends on what you want, what you owe, the type of loan, and how much time is on the calendar. This list is a conversation guide. It is not a recommendation, and it is not legal, tax, or financial advice.

  1. 1

    Pay the loan off in full.

    If you can pay the balance, or someone can help you pay it, ask the servicer for an official payoff quote — not just the amount on a statement.

  2. 2

    Reinstate.

    Bring the loan current in a lump sum and resume the regular payment. Fees can grow, so get the reinstatement amount in writing.

  3. 3

    Refinance.

    This only works if you have enough equity, qualifying income, and time, and if title is clear. Being behind often makes a refinance unavailable.

  4. 4

    Forbearance or a repayment plan.

    Short-term breathing room, if you can catch up under the plan’s terms. Paused payments are usually not forgiven. Know how the backlog will be repaid before you agree.

  5. 5

    Loan modification.

    A change to the loan so the payment may be more manageable, if you want to keep the home and can afford a payment the servicer might approve. A review does not always pause a sale date.

  6. 6

    Short sale.

    A sale for less than what is owed, which the lender has to approve. The lender’s own valuation usually controls the price it will accept, and it may say no. Junior lienholders have to agree as well.

  7. 7

    Bankruptcy.

    Only a bankruptcy attorney can advise you on this. A court filing can sometimes provide time, but it is not a decision I can make for you or with you.

  8. 8

    Let a foreclosure proceed, or do nothing.

    That is also a choice, and one you should understand — including credit, any remaining balance, and moving time — before you make it. For legal questions, talk to an attorney in your state.

A short sale is not a fire sale. If it is even on the table, the lender decides what it will accept. Other paths sometimes come up later, such as a deed in lieu or a traditional listing if the numbers actually work. Those are discussed only if they fit the facts. I will never tell you to stop paying your mortgage, and I will never tell you to stop talking to your lender.

How it works

What happens after you reach out?

Four steps. You will always know who is doing the work, and you can keep talking with your lender the whole time.

1

Tell me what’s going on.

We go over the letters, the dates, the loans, and what you want to have happen. Nothing is owed for this first conversation. If a sale or court date is close, I will say so plainly and point you to a HUD-approved counselor and, when it’s time, a foreclosure attorney in your state.

2

If keeping the home is still on the table, you do the work — I stay in touch.

I send you a self-service kit: how to find your servicer’s own forms, what a complete request usually includes, and how to reach a HUD-approved housing counselor at 800-569-4287. You make the calls and submit the paperwork. I check in by email each week so the relationship doesn’t go quiet. I am not on the phone doing the servicer work for you on this track, and I do not charge for it.

3

If a short sale may be the path, I can work with the lender on your behalf.

That only happens with your written authorization, and only where the rules allow me to do that work. A separate licensed real estate agent lists the home, shows it, and handles the contract between you and a buyer. I am not the listing agent. I deal with the servicer: the package, the follow-up, and the negotiation of the short payoff. If I cannot work the file in your state, I will tell you and help you hand it to a licensed local partner rather than leave you without a path.

4

Close it out, or change course if the facts change.

If the lender approves a short sale, we follow the conditions, payoffs, and closing. You may accept or reject that approval. If you reject it, no one owes a fee. If an option is not approved, we talk about what’s left, including help from an attorney or a HUD-approved counselor.

Two kinds of help

Hoping to keep the home, or is a short sale on the table?

These are two different kinds of help. You can start with the first and move to the second later if the facts change. You pay nothing on either track.

Help with keeping the home

What it covers
Loan modification, forbearance, a repayment plan, reinstatement, and similar options your servicer already offers
Who does the work
You do, using my guides and your servicer’s own forms. I refer you to a HUD-approved counselor (800-569-4287) when that would help.
How we stay in touch
A weekly email from me to see how things are going
What you pay
Nothing
If it doesn’t work
We can talk about whether a short sale, or another path, is worth considering

Short-sale negotiation

What it covers
Negotiating with the lender for a sale for less than what’s owed
Who does the work
I work with the lender on your behalf, with your written authorization. A separate licensed agent lists the home.
How we stay in touch
Updates while the file is active
What you pay
Nothing. If a fee is earned, the buyer pays it at closing, only after you have signed the lender’s written approval. It is shown on the settlement statement. It is never taken from your proceeds.
If it doesn’t work
You may reject the lender’s offer. If you do, no one owes a fee. You can stop working with me at any time.

I do not charge an advance fee, a retainer, or a “processing” fee to talk with a lender. Federal rules restrict that kind of charge. Referring you to a HUD-approved counselor does not end our relationship and does not stop later help, including a short sale if that becomes the path. I do not pay or receive a fee for that referral.

The lender has to accept a buyer-paid fee on the settlement statement. Some loan types and some servicers will not. If the fee is not approved in writing, it is not collected, and you still owe nothing.

Before publish — not shown as final page copy.

Settlement-statement payee, to confirm with the broker (in Virginia this is usually the brokerage, not Jacob personally): [FEE PAYEE]

Optional fee amount — do not publish a dollar figure until counsel and the broker agree: [FEE AMOUNT]

About

About Jake

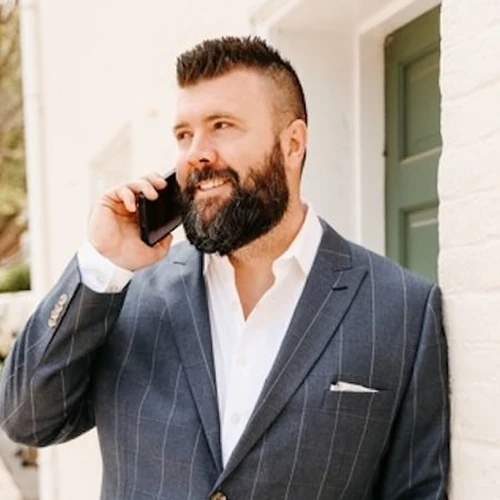
Jake Gregory

I’m Jake Gregory. I’ve been in the real estate industry for over a decade. That work has given me a real understanding of how lenders, servicers, and markets operate — and of what a homeowner is up against when a loan is in trouble.

When you’re behind on your mortgage, or you owe more than your home is worth, it can feel like you’re on your own, and like there are no options left. I want to be your advocate: someone who will sit with the facts, explain the choices in plain language, and help you take a next step that fits your situation.

[PHONE] · [EMAIL] · [SITE URL]

For professionals

Already helping a homeowner who’s behind, or who owes more than it’s worth?

I work alongside the professionals already helping the homeowner. I do not take their role, and I do not pay or accept referral fees.

For foreclosure, bankruptcy, divorce, and probate attorneys

You keep the legal work, the court, and the trustee. I handle the servicer grind: authorizations, packages, follow-up, junior liens, and payoff collection through closing. I copy you on what is sent and what comes back.

I am not a lawyer. I do not give legal advice, draft pleadings, appear in court, or share legal fees. I do not pay, offer, or accept referral fees with attorneys.

This is useful when a sale date is approaching and a complete package still needs to get in; when a loan-mod or short-sale review keeps stalling; when a Chapter 13 or Chapter 7 sale needs the lender to agree; when a divorce or estate is stuck on a house that will not sell for what is owed; or when a HELOC, HOA, judgment, or tax lien is in trouble even if the first mortgage looks current.

A court generally cannot order a short sale over a lender’s objection. I cannot promise the servicer will agree, or that a sale date will move.

Refer a matter — use the form

For real estate agents

You keep the relationship, the listing, the showings, and the contract. I do not list homes and I do not compete for your listing. If a homeowner comes to me without an agent and a listing is the right path, the homeowner chooses the agent.

I work the lender and lienholder side — paperwork, follow-up, valuation questions, and junior liens — so a file that looked stuck has a real chance to be reviewed. On a short sale, the lender still has to approve your commission. I will not promise a number the lender has not approved.

I do not pay referral fees for sending me a seller. That would be unlawful for settlement-service business. The value is a client who was not left without a path, and a file that can actually move.

Refer a listing — use the form

For investors

If you found a homeowner who needs a short payoff, a lien release, or time, you can refer the file or, when it is appropriate and fully disclosed, be the buyer. I work for the homeowner in the negotiation with the lender, not for the buyer.

If you are the buyer, your offer and your role are disclosed like any other. If your number will not work, the honest outcome may be a market short sale with another buyer. I will not take a partner’s deal out from under them. I do not promise a price, an approval, or a timeline. Legal and tax questions belong with the homeowner’s own advisors.

Refer a file or introduce a situation — use the form
FAQ

Have questions before you reach out?

Can you stop my foreclosure?

No one who is being honest can guarantee that. Starting earlier usually leaves more options open. Whether a sale date moves is up to the lender and, in some cases, the court. For legal defense, talk to a foreclosure attorney in your state. For a free second look at your options, talk to a HUD-approved housing counselor at 800-569-4287.

Does a loan-modification review automatically pause the sale?

Not always. Ask your servicer in writing and get legal advice. A complete application submitted early enough can trigger federal review rights. A late or incomplete one may not.

Are you an attorney, a HUD-approved counselor, or my lender?

No. I am not a lawyer, I do not give legal, tax, or financial advice, and I am not a HUD-approved housing counselor. I am not affiliated with any government agency, HUD, or any mortgage lender or servicer. This is not legal advice. Consult an attorney in your state.

Will you tell me to stop paying my mortgage, or to stop talking to my lender?

Never. You should keep communicating with your servicer. I will never ask you to stop.

What does this cost me?

You pay nothing. Help with a loan modification, forbearance, repayment plan, or reinstatement is provided at no charge, through guides and weekly emails. If I negotiate a short sale on your behalf, you still pay nothing. Any fee is paid by the buyer at closing, only after you have signed the lender’s written approval, and only if the lender has accepted that fee in writing. If you reject the lender’s offer, or if the sale does not close, no one owes the fee. You can stop working with me at any time.

Do you list my house?

No. A separate licensed real estate agent lists the home and handles the sale between you and the buyer. I work with the lender on the short-sale negotiation. I am not the listing agent and I am not the buyer’s agent.

Do you pay referral fees to agents or attorneys?

No. I do not pay, offer, or accept referral fees, and I do not share legal fees.

What should I do today if I have a sale date?

Write down the date. Gather the latest statements and notices. Talk to a HUD-approved counselor at 800-569-4287 and, if the date is close, a foreclosure attorney in your state. Then use the form so I can see whether there is still time to be useful. Please don’t include Social Security numbers or full loan numbers on the form.

Can I stop working with you? What if I turn down a lender’s offer?

Yes. You may stop working with me at any time. You may accept or reject any offer obtained from your lender or servicer. If you reject it, no one owes a fee.

Do you only work in Virginia?

I am based in Virginia. The self-service help and a referral to a HUD-approved counselor are available no matter where the home is. Whether I can be paid to negotiate a short sale depends on the state where the property sits, because licensing rules are set state by state. I will tell you honestly if I can work the file myself or if it should go to a licensed local partner.

If this sounds like your situation, start here.

Tell me what’s going on and any dates I should know. I review the dates first. If a sale date is close, please also contact a HUD-approved counselor and a foreclosure attorney in your state today.

Begin the form

Start here

Tell me what’s going on.

Tell me what’s going on. Please don’t include Social Security numbers or full loan numbers here.